Business
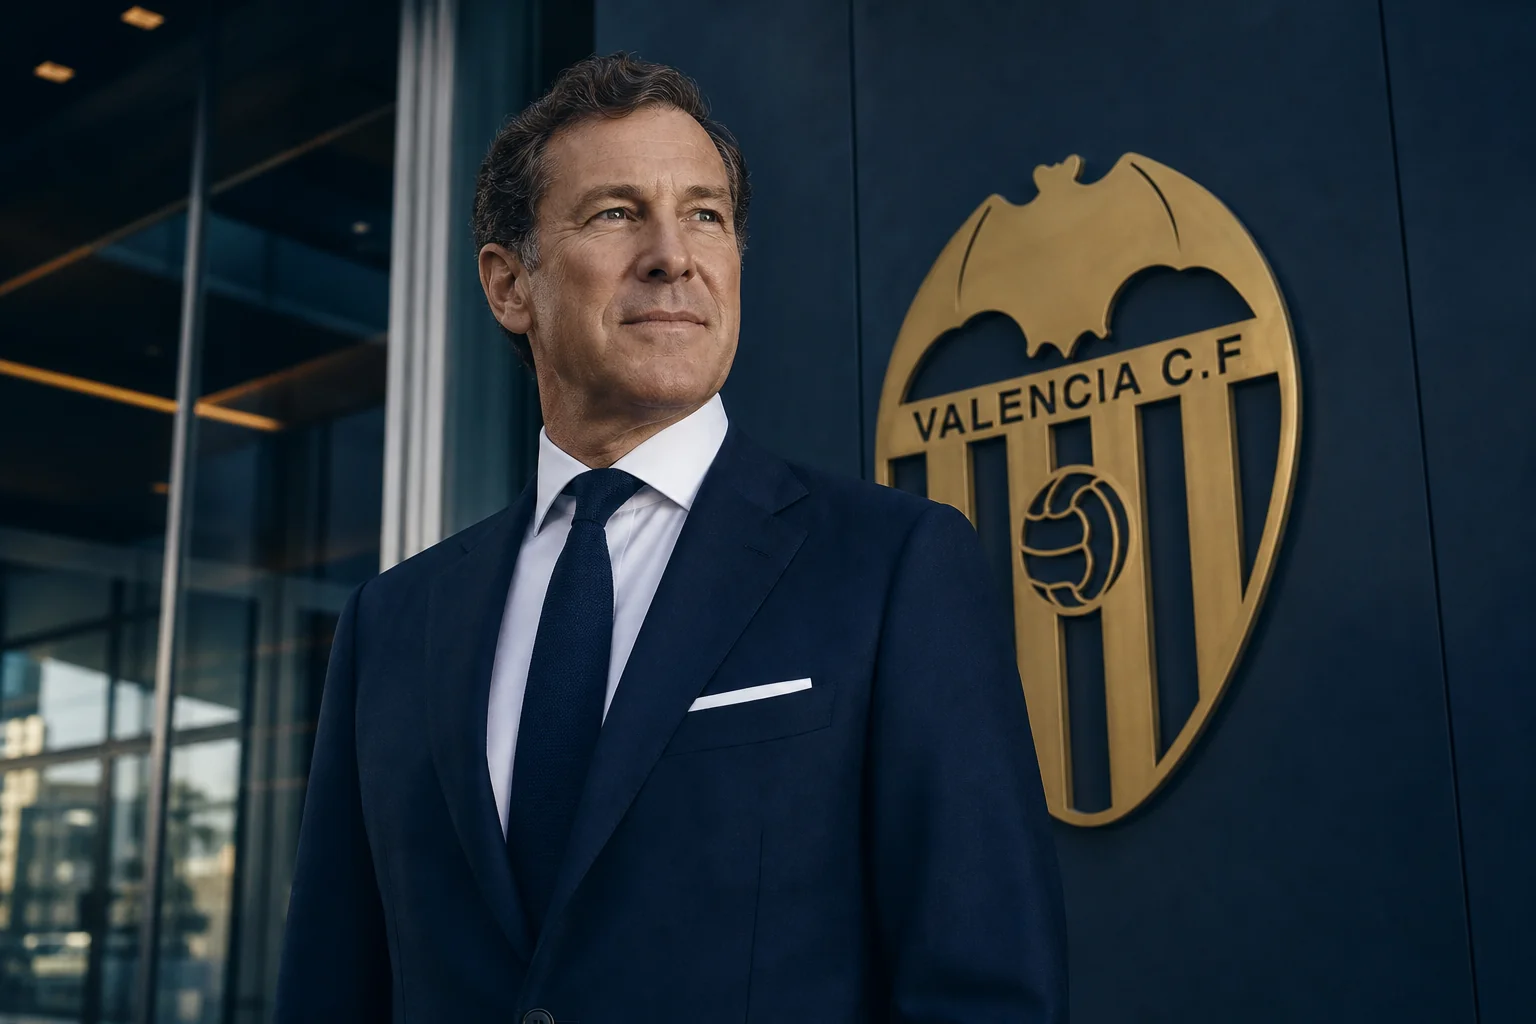
Greg Penner Expands Global Sports Portfolio With Valencia CF Investment
The Walmart chairman continues his strategic shift into international sports, securing a significant stake in the Spanis...

The buy now, pay later model is reshaping consumer behavior and credit access. With a growing user base and innovative payment options, BNPL is expanding beyond its original demographic, transforming the financial landscape for all.


As consumers and businesses continue to navigate the evolving landscape of financial transactions, the Buy Now, Pay Later (BNPL) model is emerging as a dynamic force reshaping how we think about credit and purchasing.
Once primarily associated with small, short-term loans catering to lower-income consumers, BNPL is breaking through its original mold, offering a broader array of services and innovating beyond the traditional “pay in 4” construct.
As we entered the new year, it became evident that debit was the preferred method for everyday expenditures like groceries.
Bank earnings showed that while card spending was slowing, it remained robust, with debit transactions surpassing credit volumes.
This shift is indicative of a larger trend where BNPL options are gaining traction.
According to PYMNTS Intelligence, 128 million Americans used a pay-later product from at least one alternative credit provider over the past year, contributing to a whopping $175 billion in U.S. BNPL transactions.
In a striking display of its widening embrace, BNPL providers like Klarna, Affirm, and Sezzle are branching out beyond their foundational models.
They are now introducing flexible credentials and BNPL provider-issued cards, which have been crucial in expanding the reach of short-term credit.
This evolution is seen in the usage patterns of younger generations, with 46% of Gen Z and 47% of millennials having used BNPL over the past year.
Notably, more than 40% of surveyed consumers stated that they might forgo purchases if BNPL options were unavailable.
This reflects a significant shift in consumer expectations and purchasing behavior.
Initially, BNPL’s appeal was linked to its accessibility for small-dollar transactions and lower-income demographics.
However, the profile of BNPL users is changing.
Now, six out of ten U.S. consumers who opt for this payment method earn at least $100,000 annually.
Furthermore, the merchant base is expanding, with companies like Sezzle focusing on larger enterprise-level merchants.
In their latest earnings report, Sezzle’s CEO, Charlie Youakim, highlighted emerging verticals, such as grocery sectors, where BNPL adoption is gaining momentum.
The B2B sector is also experiencing BNPL’s transformative impact.
Klarna’s partnership with Xero allows small business platform users to offer BNPL options to customers, enhancing cash flow for both buyers and businesses.
This strategic move underscores the versatility of BNPL and its potential to streamline operations across different sectors.
Recent innovations, such as Visa’s flexible digital credentials and Mastercard’s embedded BNPL options, are paving the way for seamless BNPL use both online and in-store.
These flexible credentials enable users to toggle between various payment options for specific transaction sizes, potentially allowing issuers to cross-sell additional services.
This adaptability is echoed by pure-play BNPL providers, who are working to convert debit into credit.
For instance, digital wallets are increasingly using stored debit cards across multiple transaction types, including groceries, retail, restaurants, and travel.
Financial institutions are also joining the fray, offering installment options to cater to the growing demand for flexible payment solutions.
JPMorgan Chase, for instance, provides a “Pay in 4” feature, allowing most debit card purchases between $50 and $400 to be divided into four equal payments over eight weeks.
Meanwhile, Galileo Financial Technologies is expanding its BNPL offerings for FinTechs and banks, enabling post-purchase installment payments via existing debit cards.
Affirm’s Debit Card, a Visa card, exemplifies the movement beyond “pay in 4,” allowing users to decide at checkout whether to pay in full or over time.
During a recent earnings call, Affirm’s CEO, Max Levchin, emphasized the long-term value of their customer base, highlighting that existing Affirm users who signed up through 0% promotions are prime candidates for their card, boosting lifetime value.
Affirm’s investor materials reveal a significant growth in gross merchandise value tied to the Affirm Card, increasing by 115% to $807 million year-over-year, with active cardholders more than doubling to 1.9 million.
The evolution of BNPL is more than just a financial innovation; it’s a reflection of changing consumer behaviors and expectations.
As these models continue to adapt and expand, they promise to redefine the credit economy, offering consumers and businesses alike more flexible, accessible, and versatile financial solutions.
The future of BNPL is poised to be as dynamic and transformative as the people and businesses it serves.